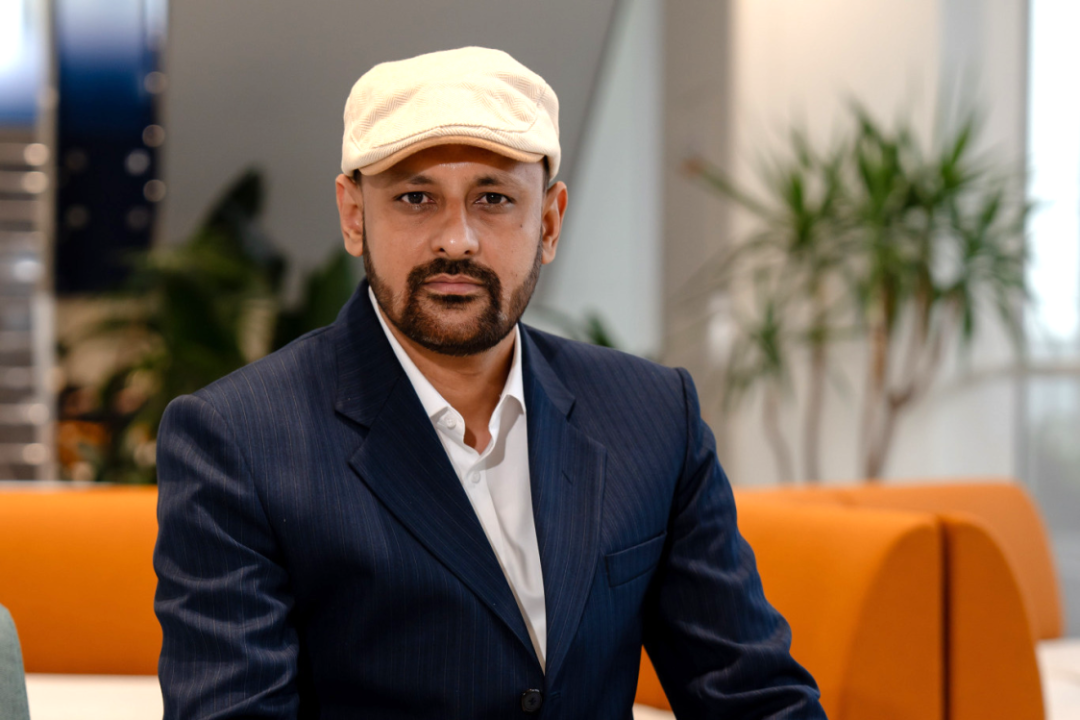
Jahidur Rahman
-
Position:Assistant Professor of Accounting
-
Office:CBPM B421
-
Email:
Educational Background
- PhD in Accountancy (Accounting)—City University of Hong Kong, Hong Kong
- MBA in Business Management—Ritsumeikan Asia Pacific University, Japan
- MBA in Accounting and Information Systems—University of Dhaka, Bangladesh
- BBA in Accounting and Information Systems—University of Dhaka, Bangladesh
Professional Qualification
- Fellow Certified Practising Accountant (FCPA)—CPA Australia
Teaching Courses
- Principles of Accounting I and II
- Intermediate Accounting, I and II
- Cost Accounting
- Financial Statement Analysis
- Advanced Accounting
- Auditing Financial Statements
- Senior Thesis in Accounting and Finance
Biography
Md Jahidur Rahman is an Assistant Professor of Accounting at Wenzhou-Kean University, China, and a Fellow of CPA Australia (FCPA). He earned his Ph.D. in Accountancy from the City University of Hong Kong, an MBA in Business Management from Ritsumeikan Asia Pacific University, Japan, and both BBA (Honors) and MBA degrees in Accounting from the University of Dhaka, Bangladesh.
His research interests include sustainability and ESG reporting, carbon accounting, corporate governance, auditing, financial reporting, artificial intelligence, digital transformation, and accounting education. His research has appeared in internationally recognized journals, including The British Accounting Review, Accounting & Finance, International Journal of Auditing, Journal of Contemporary Accounting & Economics, Advances in Accounting, Meditari Accountancy Research, Managerial Auditing Journal, and International Journal of Accounting & Information Management. He has also edited scholarly books and contributed to book chapters, international conferences, and collaborative research projects.
Dr. Rahman integrates research, data analytics, artificial intelligence, and emerging technologies into accounting education. His contributions to teaching have been recognized through the Excellence in Teaching Award, the Most Dedicative Professor Award, the Advanced Educator Award from the Wenzhou Education Bureau, and Zhejiang Provincial First-Rate Course recognition. He is actively engaged in student research supervision, curriculum development, academic reviewing, and international scholarly service.
Research Interests
- Financial accounting and corporate reporting
- Auditing and audit quality
- Artificial intelligence, machine learning, and accounting analytics
- Corporate digitalization and blockchain technology
- ESG, sustainability, and carbon accounting
- Corporate governance and family firms
Professional Experience
- Assistant Professor of Accounting- Wenzhou-Kean University, China
- Visiting Scholar- RMIT University, Melbourne, Australia
- Instructor of Accounting- City University of Hong Kong, Hong Kong
- Graduate Teaching Assistant- Ritsumeikan Asia Pacific University, Japan
- Assistant Professor of Accounting- Ahsanullah University of Science and Technology, Bangladesh
- Lecturer in Accounting- Ahsanullah University of Science and Technology, Bangladesh
Selected Publications
Edited Scholarly Books
- Rahman, M. J., Rana, T., & Zhu, H. (Eds.). (2026). Artificial Intelligence and Accounting Education: Policy, Practice and Research. Routledge, Taylor & Francis. Role: Lead/First Editor
- Rana, T., Rahman, M. J., & Öhman, P. (Eds.). (2025). Environmental, Social and Governance Accounting and Auditing. Routledge, Taylor & Francis. Role: Co-Editor
- Rana, T., Rahman, M. J., & Öhman, P. (Eds.). (2025). Carbon Accounting for Sustainability and Environmental Management. Routledge, Taylor & Francis. Role: Co-Editor
- Rahman, M. J., Zhu, H., & Rana, T. (Eds.). (forthcoming). Evolving Auditing: Technology, Sustainability, and Regulation in the Chinese Market. Springer Nature. Role: Lead/First Editor
- Zhu, H., Rahman, M. J., & Rana, T. (Eds.). (forthcoming). Sustainability, Accountability and Digitalization in Accounting. Springer Nature. Role: Co-Editor
Refereed Journal Articles (Selected)
- Zhu, H., & Rahman, M. J. (2025). Ex-ante expected changes in ESG and future stock returns based on machine learning. The British Accounting Review, 101563. [ABDC: A* | SSCI | SJR: Q1 | CABS/AJG: 3*]
- Hossain, M. M., Lema, A. C., Nahar, S., Rahman, M. J., Edirisinghe, U. C., & Bodle, K. (2026). Corporate Indigenous stakeholder engagement in sustainability reporting: Evidence from the Australian mining industry. Business Strategy and the Environment. [ABDC: A | SSCI | SJR: Q1 | CABS/AJG: 3*]
- Rahman, M. J., Zhu, H., & Yue, L. (2024). Does the adoption of artificial intelligence by audit firms and their clients affect audit quality and efficiency? Evidence from China. Managerial Auditing Journal. [ABDC: A | SSCI | SJR: Q1 | CABS/AJG: 2]
- Rahman, M. J., & Zhu, H. (2024). Predicting financial distress using machine learning approaches: Evidence from China. Journal of Contemporary Accounting & Economics, 20(1), 100403. [ABDC: A | SSCI | CABS/AJG: 2]
- Rahman, M. J., Zhu, H., & Jiang, X. (2024). Family firms, client importance, and auditor reporting behavior: Evidence from China. Meditari Accountancy Research, 32(2), 543–578. [ABDC: A | SJR: Q1]
- Rahman, M. J., & Zhu, H. (2024). Detecting accounting fraud in family firms: Evidence from machine learning approaches. Advances in Accounting, 64, 100722. [ABDC: A | CABS/AJG: 2]
- Lam, B. M., Mo, P. L. L., & Rahman, M. J. (2024). Secrecy culture, client importance, and auditor reporting behavior: An international study. Managerial Auditing Journal, 39(2), 113–137. [ABDC: A | SSCI | SJR: Q1 | CABS/AJG: 2]
- Rahman, M. J., Rana, T., Xu, Y., & Öhman, P. (2024). Bridging BI and AI: Enhancing operational efficiency in the Chinese financial sector. Journal of Global Information Management, 32(1), 1–27. [ABDC: A | SSCI | SJR: Q1 | CABS/AJG: 2]
- Rahman, M. J., Zhu, H., Zhang, Y., & Hossain, M. M. (2024). Effect of female representation in audit committees on non-audit fees: Evidence from China. Meditari Accountancy Research. [ABDC: A | SJR: Q1]
- Hossain, M. M., Rana, T., Nahar, S., Rahman, M. J., & Lema, A. C. (2023). Regulatory influence on sustainability reporting: Evidence from Murray–Darling Basin Authority in Australia. Meditari Accountancy Research, 31(5), 1386–1409. [ABDC: A | SJR: Q1]
- Rahman, M. J., & Zhu, H. (2023). Predicting accounting fraud using imbalanced ensemble learning classifiers: Evidence from China. Accounting & Finance, 63(3), 3455–3486. [ABDC: A | SSCI | SJR: Q1 | CABS/AJG: 2]
- Cahan, S., Lam, B. M., Li, L. Z., & Rahman, M. J. (2021). Information environment and stock price synchronicity: Evidence from auditor characteristics. International Journal of Auditing, 25(2), 332-350. [ABDC: A | SSCI | SJR: Q1 | CABS/AJG: 2]
- Rahman, J., Yuchen, L., Öhman, P., & Rana, T. (2026). Impact of COVID-19 on audit fees in Chinese family firms: Exploring the roles of ownership, management and directorship. Journal of Accounting in Emerging Economies, 16(1), 115–137. [SJR: Q1 | CABS/AJG: 2]
- Hossain, M. M., Rahaman, M. M., Rahman, M. J., Lema, A. C., & Hassan, A. (2025). Australian public universities' response to COVID-19. Journal of Public Budgeting, Accounting & Financial Management, 37(1), 70–85. [SJR: Q1 | CABS/AJG: 2]
- Rahman, M. J., Wu, Q., & Zhu, H. (2024). Corporate social responsibility in times of social distancing: Evidence from China. Business Ethics, the Environment & Responsibility. [SSCI | SJR: Q1 | CABS/AJG: 2]
- Rahman, M. J., Xuan, J., Zhu, H., & Hossain, M. M. (2024). Accounting fraud and corporate sustainability: Chinese listed companies. Journal of Financial Crime, 31(3), 558–574. [SJR: Q1]
- Rahman, M. J., & Jie, X. (2024). Fraud detection using fraud triangle theory: Evidence from China. Journal of Financial Crime, 31(1), 101–118. [SJR: Q1]
- Al Masud, A., Islam, M. T., Rahman, M. K. H., Or Rosid, M. H., Rahman, M. J., Akter, T., & Szabó, K. (2024). Fostering sustainability through technological brilliance: A study on the nexus of organizational STARA capability, GHRM, GSCM, and sustainable performance. Discover Sustainability, 5(1), 325. [SJR: Q1]
- Hossain, M. M., Rahaman, M. M., & Rahman, M. J. (2023). COVID-19 corruption in the public health sector—Emerging evidence from Bangladesh. Health Policy and Planning, 38(7), 799–821. [SSCI | SJR: Q1]
- Rahman, M. J., Zhu, H., & Beiyi, S. (2023). Is COVID-19 a turning point? Evidence from CEOs' investment behavior and risk tolerance. International Journal of Emerging Markets. [SSCI | SJR: Q1]
- Rahman, M. J., Zhu, H., & Hossain, M. M. (2023). Auditor choice and audit fees through the lens of agency theory: Evidence from Chinese family firms. Journal of Family Business Management, 13(4), 1248–1276. [SJR: Q1]
- Rahman, M. J., Zhu, H., & Chen, S. (2023). Does CSR reduce financial distress? Moderating effect of firm characteristics, auditor characteristics, and COVID-19. International Journal of Accounting & Information Management, 31(5), 756–784. [SJR: Q1 | CABS/AJG: 2]
- Rahman, M. J., & Zheng, X. (2023). Whether family ownership affects the relationship between CSR and EM: Evidence from Chinese listed firms. Journal of Family Business Management, 13(2), 373–386. [SJR: Q1]
- Rahman, M. J., Ding, J., Hossain, M. M., & Khan, E. A. (2023). COVID-19 and earnings management: A comparison between Chinese family and non-family enterprises. Journal of Family Business Management, 13(2), 229–246. [SJR: Q1]
- Rahman, M. J., & Chen, X. (2023). CEO characteristics and firm performance: Evidence from private listed firms in China. Corporate Governance: The International Journal of Business in Society, 23(3), 458–477. [SJR: Q1 | CABS/AJG: 2]
- Rahman, M. J., & Ziru, A. (2023). Clients' digitalization, audit firms' digital expertise, and audit quality: Evidence from China. International Journal of Accounting & Information Management, 31(2), 221–246. [SJR: Q1 | CABS/AJG: 2]
- Khan, E. A., Cram, A., Wang, X., Tran, K., Cavaleri, M., & Rahman, M. J. (2023). Modelling the impact of online learning quality on students' satisfaction, trust and loyalty. International Journal of Educational Management, 37(2), 281–299. [SJR: Q1]
- Rahman, J., & Jin, Y. (2023). The control of tax corruption: Evidence from nonfungible token market in China. Journal of Money Laundering Control, 26(5), 1066–1082. [SJR: Q1]
Note: Selected refereed journal articles are listed above. For a complete and updated list, please visit my Google Scholar Profile:
https://scholar.google.com/citations?user=T8YZah8AAAAJ&hl=en&oi=ao
Selected Scholarly Book Chapters
- Rahman, M. J., Rana, T., Zhu, H., Zheng, J., Deng, X., Wang, Q., & Chang, K. (2026). Transforming cost accounting education with generative AI: Opportunities and challenges. In Handbook of Generative Artificial Intelligence in Accounting and Business Education. Springer Nature.
- Rahman, M. J., Rana, T., Zhu, H., Chen, C., & Siddique, A. (2026). Generative AI in accounting education: Student perceptions and effectiveness in an advanced accounting course. In Handbook of Generative Artificial Intelligence in Accounting and Business Education. Springer Nature.
- Rahman, M. J., Rana, T., & Zhu, H. (2026). Generative AI’s impact on student engagement through technology acceptance and cognitive theories. In Handbook of Generative Artificial Intelligence in Accounting and Business Education. Springer Nature.
- Rahman, M. J., Rana, T., & Zhu, H. (2026). AI in higher education—A paradigm shift in accounting and business pedagogy. In Artificial Intelligence and Accounting Education: Policy, Practice and Research. Routledge.
- Rahman, M. J., Rana, T., & Zhu, H. (2026). AI-powered personalization in accounting pedagogy: A TAM-SDT integration framework. In Artificial Intelligence and Accounting Education: Policy, Practice and Research. Routledge.
- Rahman, M. J., Rana, T., Zhu, H., & Wang, Z. (2026). Theorizing AI in accounting education: Extending cognitive load theory, technology acceptance model, and self-regulated learning for text summarization. In Artificial Intelligence and Accounting Education: Policy, Practice and Research. Routledge.
- Rahman, M. J., Rana, T., & Zhu, H. (2026). Policy, practice, and future research on AI in accounting education. In Artificial Intelligence and Accounting Education: Policy, Practice and Research. Routledge.
- Rana, T., Rahman, M. J., & Öhman, P. (2025). ESG accounting for performance measurement, risk management, and accountability. In Environmental, Social and Governance Accounting and Auditing. Routledge.
- Rahman, M. J., Rana, T., Zhu, H., & Zhuge, L. (2025). The relationship between ESG disclosure, financial reporting quality, and investment efficiency. In Environmental, Social and Governance Accounting and Auditing. Routledge.
- Rahman, M. J., Rana, T., Zhu, H., & Zeyu, C. (2025). Green accounting in China: Challenges, opportunities, and future directions. In Carbon Accounting for Sustainability and Environmental Management. Routledge.
- Rahman, M. J., Rana, T., Zhu, H., & Xiaowei, Y. (2025). Mandatory or voluntary? Explore the effectiveness of Chinese environmental information disclosure policy. In Carbon Accounting for Sustainability and Environmental Management. Routledge
- Rana, T., Rahman, M. J., & Öhman, P. (2025). Management control, performance measurement, and climate risk management perspectives for carbon accounting. In Carbon Accounting for Sustainability and Environmental Management. Routledge.
Note: Selected book chapters are listed above. For a complete list, please visit my Google Scholar profile
https://scholar.google.com/citations?user=T8YZah8AAAAJ&hl=en&oi=ao
Selected Recent Conference Presentations
- Lam, B. M., Li, L. Z., & Rahman, M. J. (2026). Religiosity and Business Strategy. Accounting and Finance Association of Australia and New Zealand (AFAANZ) Conference, Australia.
- Rahman, M. J., & Zhu, H. (2024). Blockchain Adoption Propensity and Accounting Fraud: Insights from Machine Learning Evidence. American Accounting Association (AAA) Conference.
- Cheng, C. S. A., Lam, M., Lui, G., & Rahman, M. J. (2024). How Do External Monitoring Affect Operational Efficiency? Accounting and Finance Association of Australia and New Zealand (AFAANZ) Conference, The Cordis Hotel, Auckland, New Zealand, 30 June–2 July 2024.
- Rahman, M. J., & Zhu, H. (2023). Detecting Accounting Fraud in Family Firms: Evidence from Machine Learning Approaches. American Accounting Association (AAA) Conference, 4 August 2023.